Asset protection is usually discussed in financial terms. The conversation revolves around property, investments, stocks and bonds, banking relationships, business interests, and the structures used to preserve wealth over time. For those thinking internationally, it can extend to different currencies, jurisdictions, overseas investments, and the risks that come from keeping too much wealth within a single country or financial system.
All of that matters. But it overlooks the most important asset in the equation: the person who owns it.
A useful way to think about genuine asset protection is as a three-legged stool. The first leg is the traditional one: protecting and diversifying wealth. The second is health, without which the value of everything else changes very quickly. The third is liberty: maintaining the legal and practical freedom to choose where to live, particularly when circumstances at home change.
Assets, health, and liberty. Together, they provide a much more complete definition of protection. The objective is not simply to preserve a balance sheet. It is to protect the life that wealth was built to support.
The First Pillar: Protecting Your Assets
Financial diversification is one of the oldest principles of investing. Few serious investors would willingly place their entire portfolio into a single company or asset class. Spreading risk across equities, fixed income, property, cash, and other investments is considered basic financial discipline.
International asset protection applies a similar principle at a different level. Someone can own hundreds of individual investments and still have considerable concentration risk if those assets are held through the same financial system, in the same country, and predominantly in the same currency. The investments themselves may be diversified, while the structure surrounding them is not.
This is why international asset protection should not be confused simply with owning physical assets overseas. An apartment in Spain, a piece of land in Central America, or a second home in the Caribbean can certainly form part of an international portfolio, but physical property is only one component.
Stocks, bonds, investment accounts, businesses, retirement assets, cash, and banking relationships can all form part of the international diversification conversation. The important question is not simply what someone owns, but where those assets are held and to which financial, legal, and political systems they are ultimately exposed.
There is also an important distinction between legitimate international diversification and the outdated idea that offshore planning is about concealing wealth. Proper international asset protection is about legal structuring, transparency, diversification, and resilience. Tax and reporting obligations remain, regardless of where assets are held.
The objective is far simpler: avoiding unnecessary concentration. Political environments change. Tax rules change. Currencies fluctuate. Banking regulations evolve. Governments introduce new legislation, and financial institutions themselves can fail. None of this means that everyone should immediately move their wealth overseas. It means that relying entirely upon one jurisdiction deserves the same scrutiny as relying entirely upon one investment.
The best time to establish alternatives is usually before they are needed. This principle sits at the heart of any serious Plan B. A Plan B is not necessarily an escape plan and it does not require believing that disaster is imminent. It is simply an acknowledgment that circumstances can change, sometimes much more quickly than expected, and that diversification provides choices when they do.
The Second Pillar: Protecting Your Health
Financial assets receive enormous attention because their value is easy to measure. Health is harder to quantify, yet it is arguably the most valuable asset anyone possesses.
A carefully protected portfolio has limited value if poor health prevents its owner from enjoying the life it was designed to fund.
Health therefore belongs within any broader discussion about asset protection, particularly for people considering international living. Moving abroad is often discussed through the lens of tax, property prices, residency requirements, and cost of living. Healthcare deserves to sit alongside every one of those considerations.
The relevant questions go well beyond whether a country has hospitals. What is the standard of private and public healthcare? How quickly can specialists be accessed? What does private insurance cost? Does residency provide access to the national healthcare system? What happens in an emergency? How easily can someone receive treatment for an existing condition?
For retirees, these questions can become particularly important. A destination that looks inexpensive on paper can become considerably less attractive if high-quality healthcare requires regular travel to another city or country. Conversely, a country with affordable private healthcare and excellent specialists can offer a quality of life that cannot be captured in a simple cost-of-living comparison.
Protecting health also extends beyond medical treatment. Where someone lives influences how they live. Climate, diet, access to nature, walkability, pollution, working culture, social connection, and everyday stress all shape health over time. One of the reasons relocation can have such a profound effect on people is that a new environment often changes daily habits before any conscious attempt at reinvention begins.
A person who moves from a car-dependent environment to a walkable Mediterranean town may suddenly walk several miles a day. Someone leaving an intensely expensive city may discover that lower living costs allow them to work less. Better weather can mean more time outdoors. A slower pace of life may create more time for exercise, cooking, family, and sleep.
None of these things guarantees good health, of course. But they demonstrate why health and international planning are more closely connected than they initially appear.
There is little point spending decades creating financial freedom only to treat physical well-being as an afterthought. Wealth is supposed to create choices and improve quality of life. Protecting the person who owns that wealth should therefore be every bit as deliberate as protecting the wealth itself.
The Third Pillar: Protecting Your Liberty
The third pillar is liberty, and this is where second residency and second citizenship become genuine asset-protection tools rather than simply travel or lifestyle products.
The obvious benefits of a second residency are easy to understand. It can allow someone to spend more time in another country, establish a home overseas, access local services, and in some cases create a pathway toward permanent residence or citizenship.
But its deeper value is optionality. A second residency gives someone the legal right to live somewhere other than their home country. A second citizenship can go further, creating permanent rights in another nation and, depending on the passport involved, potentially across a much wider group of countries.
That freedom has value even when it is never used.
Most people establishing a Plan B are not preparing to abandon their home country. Nor do they need to be unhappy with where they currently live. The point is to ensure that another option exists if circumstances change.
Those circumstances do not have to be dramatic. A family may decide that another country offers better educational opportunities for their children. A retiree may want better weather or more affordable healthcare. An entrepreneur may find a more attractive environment for building a business. Tax rules may change. Political conditions may become less comfortable. Personal priorities may simply evolve.
The critical difference is between having the option to move and needing to begin applying for that option after the need has already arisen. Residency and citizenship programs change frequently. Governments increase investment thresholds, alter qualification rules, introduce physical-presence requirements, or close programs altogether. Even relatively straightforward applications can require months of document gathering, background checks, apostilles, translations, and government processing. That makes time an important component of liberty.
Someone who establishes a second residency years before needing it has the luxury of making decisions slowly. Someone attempting to secure one during a personal, political, or financial crisis does not.
A second residency is therefore best understood in much the same way as many other forms of protection. Its greatest value may be knowing that it is there.
Why the Three Pillars Belong Together
Assets, health, and liberty are often treated as three entirely separate subjects. In practice, they reinforce one another. International financial diversification can provide access to capital when circumstances change. A second residency can provide access to another healthcare system and another place to live.
Financial security can make it possible to relocate without immediately needing local employment. Good health makes it possible to travel, work, and enjoy the opportunities that wealth and mobility create.
Weakness in one area can also undermine the others.
Consider someone with substantial wealth but no international mobility. They may have the financial means to relocate but no automatic right to remain in the country they would choose. Someone with multiple residencies but all of their financial assets concentrated in one jurisdiction has diversified their physical location without necessarily diversifying their financial exposure. Someone who has meticulously protected both but neglected their health may discover that neither delivers the quality of life they expected.
A resilient Plan B therefore looks at the whole picture. This does not require collecting passports, opening accounts in a dozen countries, or creating unnecessarily complicated offshore structures. Complexity for its own sake is rarely useful. The objective is to identify genuine points of concentration and decide where additional options would materially strengthen an individual or family’s position.
For one person, that might mean obtaining residency in a country where they already spend several months each year. For another, it could mean diversifying part of an investment portfolio internationally. For someone approaching retirement, access to excellent and affordable healthcare may be the priority.
There is no universal structure because there is no universal life to protect. What matters is understanding that asset protection should ultimately be measured by resilience rather than simply by the value of the assets involved.
Thirty Years of Presidents’ Week
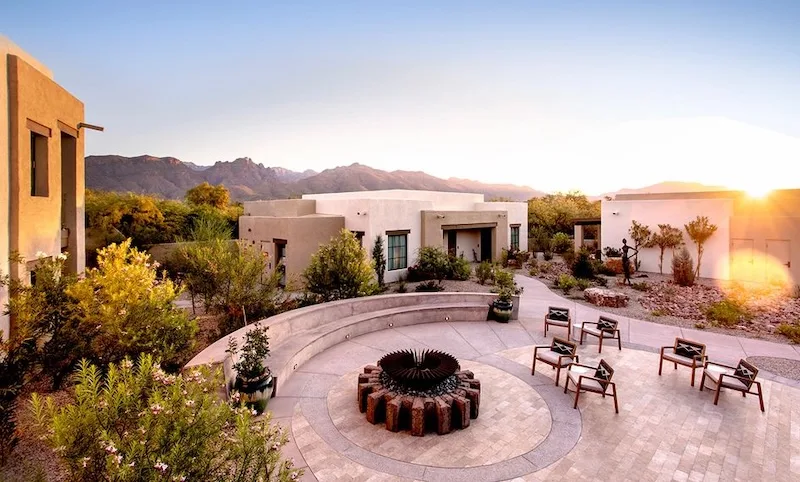
This broader view of asset protection is particularly relevant to the 30th Annual Presidents’ Week, taking place from November 9 to 13, 2026, at Canyon Ranch in Tucson, Arizona.
The event is hosted by Joel Nagel, an international attorney who has spent decades working in international asset protection, cross-border business, tax and estate planning, global investment, and residency and citizenship strategies. Through his legal practice and international work, Nagel has advised clients on many of the issues that have become increasingly important to internationally minded families: how to structure assets across borders, how to reduce unnecessary jurisdictional concentration, and how to build greater flexibility into long-term planning.
Presidents’ Week has developed around those same questions. Rather than approaching international planning as a collection of isolated products, the conference brings together specialists across areas including international asset protection, tax and estate planning, offshore structures, investments, second residency, and citizenship.
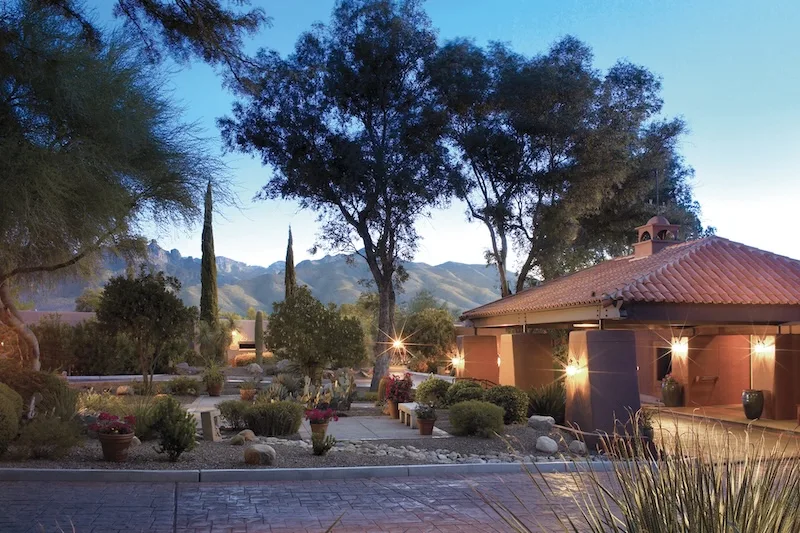
The setting for the 2026 gathering adds an interesting dimension. Canyon Ranch is one of America’s best-known wellness destinations, and its focus on health means this year’s event naturally brings together the three pillars of asset protection: wealth, health, and liberty.
Alongside discussions about international financial planning and global mobility, attendees have access to Canyon Ranch’s wider wellness environment, with fitness, spa, nutrition, and other health-focused facilities forming part of the experience.
It is an appropriate setting for a conversation that can too easily become dominated by numbers. After all, the purpose of international planning is not simply to create the cleverest structure or accumulate the greatest number of assets. Nor is obtaining a second residency particularly meaningful simply because another card can be placed in a wallet.
The value lies in what those things make possible. Financial resilience provides security. Health allows that security to be enjoyed. International mobility provides the freedom to choose where that life takes place.
Protecting More Than Money
The concept of asset protection has traditionally focused on preserving wealth from identifiable risks. That definition remains important, but it is no longer sufficient for an increasingly international world.
Assets themselves are only one part of what people spend their lives building.
A home, investment portfolio, retirement account, or business matters because of what it provides: security for a family, independence in retirement, the ability to travel, the freedom to stop working, or the opportunity to leave something behind for the next generation.
Protecting those assets internationally can make that foundation stronger. Protecting health makes it possible to enjoy what has been built. Protecting liberty through second residency or citizenship ensures that the place in which that life is lived does not have to be determined entirely by circumstances outside an individual’s control. That is the three-legged stool of modern asset protection.
Assets. Health. Liberty.
Each supports the others, and none should be considered entirely in isolation. Because the ultimate purpose of asset protection is not simply to make sure that wealth survives.
It is to make sure the person, the choices, and the life behind that wealth are protected too.
International Asset Protection: Common Questions
What is international asset protection?
Spreading wealth across more than one financial, legal and political system so that no single country, currency or institution is a point of failure. It covers banking, investments, property and business interests, not just owning property overseas.
Is international asset protection legal?
Yes, when it is done properly. Legitimate international asset protection is about legal structuring, transparency and diversification, not concealing wealth. Tax and reporting obligations stay in place wherever the assets are held.
Why does health belong in asset protection?
Because a protected portfolio has limited value if its owner cannot enjoy the life it was built to fund. For anyone considering living abroad, healthcare quality, access to specialists and insurance costs deserve the same weight as tax and cost of living.
When should you get a second residency?
Before you need it. Residency and citizenship programs change often, thresholds rise and programs close, and even simple applications take months of documents and processing. Applying early lets you decide slowly rather than during a crisis.
Presidents’ Week 2026
The 30th Annual Presidents’ Week, hosted by international attorney Joel Nagel, takes place from November 9–13, 2026, at Canyon Ranch in Tucson, Arizona. The program brings together international asset protection, tax and estate planning, global investment, second residency and citizenship, and health and wellness.
For more information about Presidents’ Week or to reserve your place, contact Mary directly at [email protected]
Learn more about Presidents’ Week 2026
About the Author
Contact Author
"*" indicates required fields
Stay Ahead on Every Adventure!
Stay updated with the World News on Escape Artist. Get all the travel news, international destinations, expat living, moving abroad, Lifestyle Tips, and digital nomad opportunities. Your next journey starts here—don’t miss a moment! Subscribe Now !
Asset protection is usually discussed in financial terms. The conversation revolves around property, investments, stocks and bonds, banking relationships, business interests, and the structures used to preserve wealth over time. For those thinking internationally, it can extend to different currencies, jurisdictions, overseas investments, and the risks that come from keeping too much wealth within a single country or financial system.
All of that matters. But it overlooks the most important asset in the equation: the person who owns it.
A useful way to think about genuine asset protection is as a three-legged stool. The first leg is the traditional one: protecting and diversifying wealth. The second is health, without which the value of everything else changes very quickly. The third is liberty: maintaining the legal and practical freedom to choose where to live, particularly when circumstances at home change.
If you'd like to read the full story, simply enter your email to subscribe to our newsletter.
For even more expert insights, unmissable resources, and exclusive invites, explore our premium subscription offers here.
OR
Already a Subscriber? Click here to login
Subscription required
You've reached your limit of free articles. For full access to Escape Artist, and all of our insights on travel, moving abroad, and the digital nomad life, click here to Subscribe.
Already a Subscriber? Log in here